


Have you ever taken a deep dive into how health insurance works? I know I didn’t for quite a while as it just seemed like a necessary part of life.
Let’s simplify it: if you go the traditional route, you pay a monthly premium to cover the routine costs of your insurance company.
According to 2026 Marketplace data, the average health insurance premium is around $741 per month before tax credits although what you actually pay can vary significantly based on your age, location, household income, family size, and plan.
Keep in mind, this premium doesn’t count towards your deductible or out-of-pocket maximum.
I went ahead and did a little research for you by pretending to sign up for Blue Cross Blue Shield (BCBS) of Texas, just to get some real numbers based on my zip code:
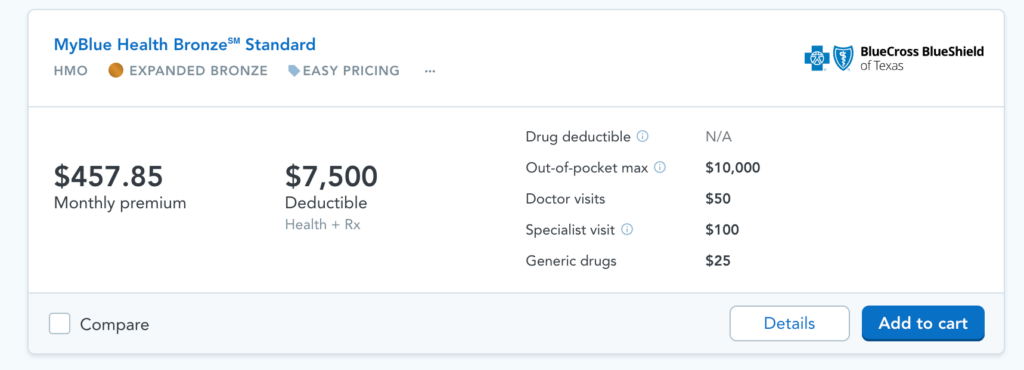
Then you have a deductible which is how much you have to pay in medical expenses every year before the insurance company will contribute a dime. According to the IRS, your deductible can be anywhere between $1,400 to $7,500.
Even after hitting your deductible, you’re still on the hook for coinsurance where you split the cost of health care services with your insurance company. For instance, your insurer might cover 80%, leaving you to cover the remaining 20% until you hit your plan’s out-of-pocket maximum.
Then there’s the copay which you cover in full for each provider visit until you reach your out-of-pocket maximum.
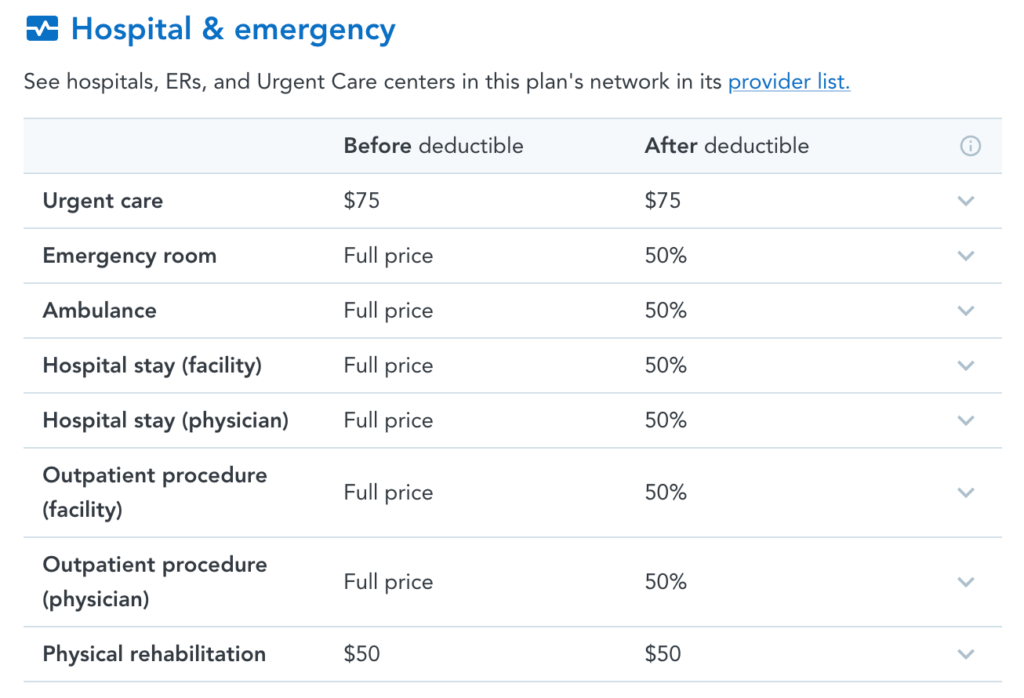
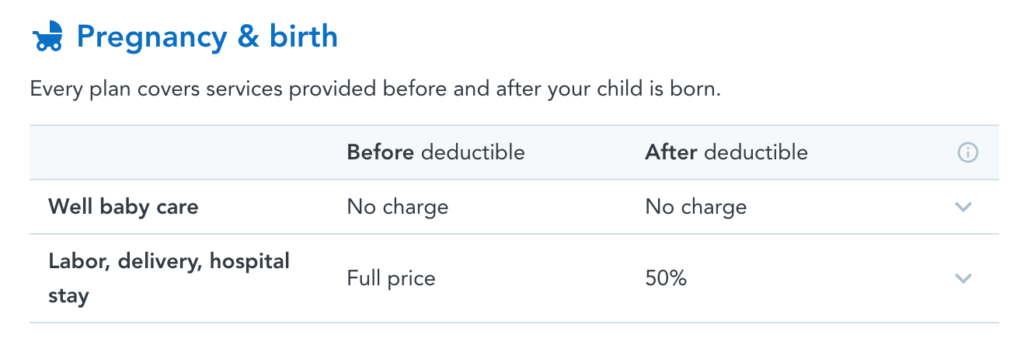
Here’s the breakdown from Blue Cross Blue Shield of Texas on what my financial responsibility would look like before and after meeting the deductible:
Let’s play pretend
Suppose I sign up for BCBS of Texas at about $457.85 per month. That adds up to $5,494 a year, solely covering the insurance company’s routine costs. Not a dime of that goes toward my deductible.
So, according to BCBS of Texas, my deductible is $7,500 per person. This means I’d have to pay the annual premium of $5,494 plus $7,500 in medical expenses before my insurance even starts contributing with coinsurance. BCBS typically covers only about 40-50% of the bill after that. If I had a year of high medical expenses, I could expect to pay $15,494 ($1,291 per month).
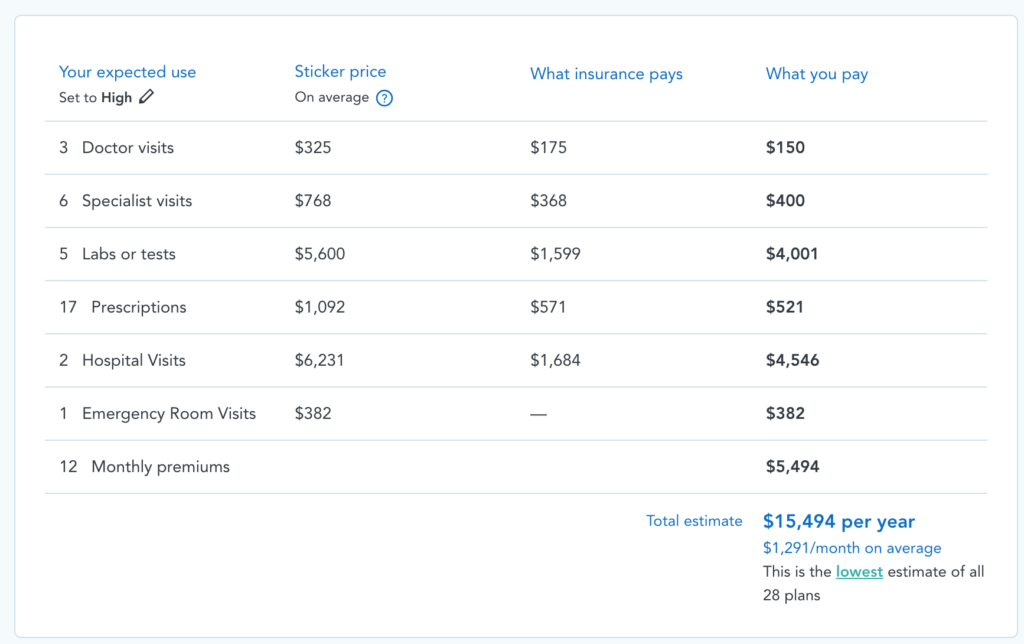
And this estimate is just for one person. Adding a spouse or children can increase those costs even more, depending on the plan you choose and your family’s healthcare needs. Remember, these companies are FOR PROFIT.
On top of that, I’m limited to which providers are in-network.
I never questioned health insurance. I assumed it was the only option…
That is, until I found Christian Healthcare Ministries (CHM), an alternative to traditional health insurance.
After thorough research, I chose to invest in our healthcare differently, aligning it more closely with my approach to and use of healthcare services.
Let me explain
I work hard to be a healthy person. That means I’m not going to conventional medical doctors regularly and I typically only step into that system when I truly need it. So, I wanted a healthcare cost solution where I could freely choose the providers and services that work best for me and my daughter. I know I’m going to pay out of pocket for some of the extra (or potentially ineligible) expenses that come with the way I choose to care for our health, but I also wanted sufficient support for the bigger, unexpected things without the monthly cost of traditional health insurance. That’s where CHM comes in!
I originally joined CHM about six years ago, around the time I was pregnant with my daughter. With my previous conventional health insurance, I knew I would have to pay entirely out of pocket for the home birth I wanted because it wasn’t covered. I also vividly remember needing a bag of IV fluids during my first trimester and being charged $1,200 at urgent care, even with insurance. Those experiences really shaped what I wanted healthcare to look like for us moving forward.
Now, as a single mom, having something in place that supports both of us feels even more important. My daughter is six now and as she’s getting older, more active, playing sports, riding bikes, and just doing all the things that come with being a kid, I want to know we have support for the unexpected while still having the freedom to make the healthcare choices that make the most sense for us.
With my CHM Gold membership, 100% of my eligible bills are reimbursed after meeting my Personal Responsibility. I’m able to have support for the bigger medical expenses without feeling restricted in the providers I choose or how I choose to care for our health. Eligible maternity expenses can include prenatal care, home birth, midwives, postpartum care (including eligible physical therapy expenses), and up to $125,000 per illness for eligible medical expenses. As a health cost sharing ministry, not insurance, CHM gives me the flexibility to prioritize what matters most to me and my daughter.
It feels like we’re getting the best of both worlds!
For my daughter and I with CHM’s Gold membership, we’re paying $598 a month ($299 per person). For reference, if we both had the MyBlue Health Bronze℠ Standard plan outlined above, it would be $746 a month ($1,776 more per year) with a much higher deductible than my Personal Responsibility is with CHM.
If you’re a parent with multiple children, there’s no need to worry. CHM simplifies things with a unit system. A single individual counts as one unit, a married couple as two units, and a family, no matter how many kids, as three units. So, if you’re married with five children, the most you’ll pay for CHM Gold is $299 per unit for three units, totaling $897 a month.
And just as a reminder, Christian Healthcare Ministries isn’t health insurance. It’s a health cost-sharing program that operates as a nonprofit within a biblical community.
Learn more by visiting Christian Healthcare Ministries.


